Category: Anti-Consumer Hall of Shame

  • How Amazon lost another Customer

    Screenshot showing Kindle's screen of my Kindle Rewards program

    I write a semi-regular column about indie ebooks, and I use all sorts of tricks to discover ebook deals on the Amazon USA store.

    Recently in good Pavlovian fashion, I was chasing 300 points in the Kindle Rewards program to qualify for a $3 Kindle credit. Some of my points were about to expire at the end of the month, so I bought a few more ebooks on the last day of the month (and indeed at 11:00 PM on the last day of the month. Finally I reached 300 points! Horray! I finally earned my bonus credit!)

    The Kindle Rewards showed that I already had 278 points, and I had bought two ebooks which gave me 22 points, leaving me with exactly 300 points. I was a winner!

    Wait, 22 of the points were pending. That’s not a problem, right? From Amazon’s website:

    The Amazon website says: What are pending points?
    Pending points are Kindle Points you’ve earned but aren’t available to use just yet. When you buy an eligible Kindle book, these points will appear as “pending” in your account. Most pending points become available to use within a few hours, but it may take up to 48 hours or more. Check your points balance anytime at amazon.com/kindlerewards.

    That’s okay, I thought. Amazon just needed time to reconcile purchases with Kindle Rewards. Eventually the points would be credited, and Amazon.com would know that those 22 points were attained before the 61 points would expire. Right?

    The next morning, I went to check my Kindle Rewards balance. Instead of showing 300 points, it showed that I had 249 points. In other words, it had subtracted the 61 points before it decided to credit the 22 pending points.

    I contacted customer service at Amazon. This seemed like an easy problem to fix. Either they could add the requisite number of Kindle Rewards points or just go ahead and credit my account $3.

    Amazon’s Customer Service: Death by AI

    But Amazon help/customer service kept directing me to its CSR chatbots. I wrote a fairly succinct description of my problem:

    I reached the 300 goal in time; therefore I should be entitled to the reward that Amazon advertised.

    Here is how you can solve the problem. It’s simple. You need to add additional points to my Kindle Rewards so that I qualify for the $3 reward. If you cannot offer me that or something equivalent, then I shall insist on refunding every ebook I purchased yesterday. Can you help make me a happy customer again? Thanks.

    This seemed like an easy customer service problem to solve. I had the evidence, and the agent had access to my purchase information.

    The CSR chatbot couldn’t accept my text except in 700 character chunks. So I copied the text 700 characters at a time. I knew that the AI-bots would probably not be able to help, but at least it could escalate the issue or give me a link to a live human or phone number.

    But the chatbot kept repeating itself — explaining the Rewards program, explaining how to redeem my points, explaining how to refund an ebook. I kept asking for a human operator, and the chatbot kept asking me to provide more context. In other words, I the human was asked to keep trying (and using my time and energy) to continue using the chatbot when it was obvious the chatbot was not programmed to help me or refer me to another place where I might find an answer.

    I continued the chat for 15-20 minutes, growing angrier while the chatbot kept asking me to provide more context. Finally, I decided how I would solve the issue: I would refund all my purchases from the previous night and stop buying Kindle ebooks! And then I decided: if Amazon cares so little about me as a customer that it made it impossible to resolve this piddly problem, then why should I continue buying ebooks from Amazon?

    Transitioning away from the Kindle Platform — The Pain Involved

    I have long pondered how I might go away from the Kindle Platform.More than many I am aware how absolutely Amazon dominates the ebook market. Even with that, I acknowledge that the Kindle apps are very well-designed and have nice features for authors and publishers even if they offer unfair terms and offer the lowest royalties in the industry. In comparison, the ebook app for Kobo and Google are functional, but don’t work as seamlessly as Kindle. Also, the process to import your own epub files (from Gutenberg or DRM-free stores) is buggy (Google) or nonexistent (Kobo).

    Most of my ebook purchases are from Amazon, and indeed, ereaderiq’s price tracking works only for ebooks sold at the Kindle store. I’d like to say that I should limit my ebook purchases only to those sold without digital-rights-management (DRM), but practically speaking, the biggest and most visible presses don’t sell ebooks on these DRM-free stores — and even if they do, they don’t discount them often.

    You’d be surprised at how many ebooks are sold exclusively on Amazon. A decade ago Amazon introduced Kindle Unlimited/Kindle Select which required exclusivity. Amazon even runs some publishing imprints which for the most part are sold only at Amazon.

    Unfortunately, when authors or publishers run ebook sales or discounts, they often “forget” to discount the same item on the Kobo/Google/Apple/BN bookstores. I regularly encounter sale prices only on the Amazon store and nowhere else.

    In the past year or so, Amazon has granted to bigger publishers the privilege to discount their titles to $0.50. That’s great news for consumers, but the other ebook distributors haven’t done the same thing. As a result, lots of older but higher quality ebooks can be bought on Amazon for practically nothing but are still priced at 9$-11$ on Kobo.

    Finally, I have purchased a lot of things from the Amazon store, so even if I decide to buy elsewhere, I still want to have access to my Amazon purchases. I may be mad, but I’m not stupid.

    The Non-Amazon Ebook Solution

    Here are the ebook solutions for those wishing to leave Amazon:

    1. Buy only DRM-free copies from author storefronts or No-DRM stores like Smashwords. As I mentioned already, most of the bigger publishers avoid No-DRM stores. Here is a list of publishers who do sell DRM-free ebooks .
    2. Buy DRM ebooks from stores other than Amazon. That includes Apple, Kobo, Google Play, BN, Bookshop.org and several others. (Speaking as an ebook publisher, it is relatively easy to distribute my press’s ebooks on these sites).
    3. Read ebooks from a device which includes apps for your preferred ebookstore and the Kindle app. Alternatively, use a dedicated ebook reader for one vendor and then a tablet that lets you download different reading apps.

    For example, now I currently have a Kindle Paperwhite (5th generation) and a 10 inch Samsung tablet (to read purchases from Amazon, Kobo, Google Play and the Libby library app).1

    In the next year or so, I will probably be upgrading my equipment. I haven’t decided what android tablet I want (probably another Samsung), but I will definitely be buying an android 7 inch color e-ink reader. E-ink devices are really fun to read and easy on the eyes. That means either the Boox Go Color 7 (Gen II) or a BigMe B7 Color ePaper Tablet. Both seem to be excellent devices and not tied to a single ebook vendor.

    Executing the Plan to Move away from Amazon: Has it Worked?

    Do not doubt my resolve to buy from non-Amazon stores.

    But in the month after my decision, I still ended up buying 17 ebooks from Amazon. (In contrast, I bought 11 discounted ebooks from Kobo and 3 titles from Smashwords). (My purchase list is here).

    Here are why I still bought from Amazon:

    1. The Complete stories of Bernard Malamud was an ebook I had waiting for a long time to be discounted. (It was discounted to 2.99 on Amazon but nowhere else).
    2. Most of the 17 ebooks were priced at 50 cents on Amazon and nowhere else. For example, University of Texas press has a lot of 50 cent titles on Amazon which sound promising but are $10 on Kobo.
    3. A number of titles were exclusive to Amazon, so I had no choice but to buy them from there.

    Despite how it might appear, this actually is progress against the Amazon monster. I buy most of my titles in the 99 cent to 1.99 range (from which Amazon extracts 65% profit), and I would easily estimate that I have moved more than 50% of my spending dollars away from Amazon. Of course, I would like to bring Amazon purchases as close to zero as possible.

    The battle continues!

    ***********

    1.  Even though the Samsung tablet is the most practical and certainly the ideal device for reading complex ebooks with illustrations, I actually prefer reading simple ebooks from my Paperwhite ↩︎
  • BUG: Epub files uploaded to Kindle Android App fail to show hyperlinks correctly

    November 7, 2022. Happy to report that this bug has been fixed in 8.69.0.100

    Nearly 2 months ago I noticed a bug on the Android Kindle app which both perplexed and angered me. I still have a hard time believing that this bug wasn’t spotted by the Kindle Software Q&A team (It’s called a “regression bug” which is a fancy way of saying that the feature worked perfectly and then suddenly failed to work). I have a hard time believing that it still has not been repaired.

    Here is a longer description of the bug (which I also posted on the KDP Formatting forum, submitted feedback via the Kindle app, reported on the Google Play store and submitted through an Amazon ticket.

    (more…)
  • Why does Comcast require 4 months to send a $20 refund?

    Everybody has their tales of awful customer service, and I’m going to share mine.

    I paid for a family member to have Comcast broadband Internet. The price was about $30 per month for 6 months, then Comcast increased the price to the “normal” monthly price of $46.97. I switched Internet providers, and called to cancel Comcast service.

    I called and was put on hold. Then it hung up on. me I called several times again and was mysteriously hung up upon. I spent an hour trying to wait on hold, only to be hung up upon. In desperation, I sent an email to customer service and copied the email to their Vice President of Customer Relations (or something like that). Fairly soon thereafter that office got back with me, leaving a message to call back. I called back and thankfully talked to a human who gave me a number to call in Houston to cancel service.

    So I called that number.  The person in Houston billing processed the Cancellation request fairly quickly and said that they could not undo the automatic withdrawal of $46.97 which would happen on May 1, but that a refund for the remaining balance would be sent to me in a few weeks. I think the woman said  3-4 weeks, but I am not sure.

    So I waited. And waited. And waited. At the end of July  I thought, “did I ever receive that refund Comcast promised me?” I checked my bank account and was dismayed to discover they hadn’t.  Irate, I called billing and said, “Where is my refund?” The Comcast billing person replied that the refund for $21.92 was still being processed – nothing was wrong – and that in the middle of July, the refund request was close to reaching the final accounting stage of  being processed.

    “Do you realize that you’ve been keeping my money for 3 months? MY money?”

    “Don’t worry, you will be receiving the check within 2-3 weeks.”

    “Why can’t I receive it NOW?”

    “That’s not the way it works,” the woman on the telephone replied.

    “I can now transfer funds to any person or company in a matter of seconds. Why does a multibillion company like Comcast need so much time to process a $20 refund?”

    “Don’t worry, you will receive your refund in 2-3 weeks.”

    But more than 4 weeks went by, and still no refund. I called Houston Comcast again and asked when I would receive the refund. The person on the phone confirmed that the $21.92 was due to me, and that it was sent on August 22 (more than a week ago).

    “I never received it,” I said. Neither I nor my family member  at the service address had received any check from Comcast. “Can Comcast provide an estimate about when the check should arrive?”

    “It should take approximately 2-3 weeks.”

    “Yes,” I said mournfully, “that’s what the other woman said 4 weeks ago.”

    I have a theory about why Comcast requires so much time to send a refund: Pure unmitigated greed. Comcast already has my money; why on earth should it be in a hurry to give it back to me? Of course, the extra liquidity and interest is always a pleasant bonus. 

    My case  is hardly unique. Many Americans have had experienced similar delays from big companies when receiving refunds.   It can take weeks if you’re lucky. Eventually you will get your money, though if you are not paying attention, sometimes you may forget to notice that the big corporation never sent it to you. Besides losing access to that money, Americans waste  a lot of time on angry  telephone calls and emails.

    Big companies like Comcast pay no price for these kinds of delays.  They know that the amounts of these refunds are small enough that consumers won’t bother to take legal action about it.  At the same time, all of us know that if customers took 4 months to pay bills, Comcast would have cancelled service immediately (and probably turned the matter to collections). Comcast expects consumers to pay their bills on time; at the same time, they insist upon the right not to abide by that same standard of promptness.

    In the meantime, the dollars keep rolling in.

    I read online that Comcast CEO Brian Roberts earned $26 million last year. That’s almost a dollar earned for every second of every  day in the year.

    Comcast’s revenues for last year was 55.8 billion dollars. That means Comcast as a company has earned $1800 in revenue for every second of every day in the year.

    In fact, in the time it  took you to read my complaint (3 minutes), Comcast’s CEO earned $160 and the company itself earned $324,000.

    So I feel pretty sure Comcast can afford it.

    October 22, 2012 Update. Comcast finally did send the $21 refund 3 weeks after I wrote this message. I wrote this blog post mainly to shame them, but frankly, I don’t think my protestations made a single bit of difference. In the meantime, Comcast took over my apartment complex as the sole broadband provider, so I’m afraid I have to deal with them again.

  • Software Bugs are invading my dreams!

    This is the second time it’s happened now. I am so weirded out that I don’t know how to account for it.

    A few days ago at 3 AM in the morning  I was awakened by a loud rock song blaring from my computer speakers. It was so loud that I jumped out of bed and ran to my computer to turn it off. Here was the problem. I had no idea what had caused it. I checked Windows Media Player, but it wasn’t playing anything. Then I checked all 75 tabs on my Firefox browser (or more, I can’t remember). But I had no idea what I was looking for. Where was this blasted music coming from? Finally, out of frustration, I muted the speakers and began my hunt for the offending browser window.

    By then I was wide awake and wanted to approach the problem methodically. Where was this background music coming from? Did I have any youtube windows open? (Sometimes, a video will not load, but then load randomly without warning). Finally, I closed every Firefox browser and realized something scary … it was  not coming from Firefox!

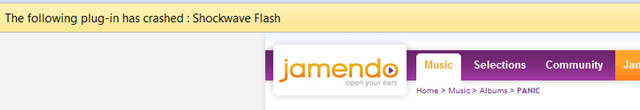
    Alas, there still was Google Chrome (mercifully, with fewer tabs open). Aha! It had to do with the Jamendo music site. As much as I loved Jamendo, their popup music player was notoriously buggy. But the browser window containing the music player was already closed! Aha, Jamendo also has an embedded music player embedded on individual pages. One of them must have started to play. I glance at the 5 remaining tabs. I see the message in the yellow bar on the top that the flash player has crashed.

    flash-crash

    I check every individual page to see if a song is playing on the embedded radio. Nothing is. However, one page, the jamendo home page shows an error message and has four embedded players inside.  And one of them is playing furiously. I’m not sure what is going on here. When the popup music player crashes, that causes the jamendo page to auto-update to an error message where one of the embedded radio stations starts playing spontaneously.  I’m not sure what causes the popup music player to crash. Was it playing before at low volumes, or did I just pause it?

    So, the result of a flash player crash is for music to start playing furiously from the home page. Wow, that’s an appropriate way to apologize to the user for a software ##$#$#.

    Last night, the same nightmare happened again! I woke up at about 4 or 5 in the morning to the sounds of some strange hard rock melody by Dada Weatherman. Same flash player crash; same auto-update to an Oops page.  This computer bug woke me up twice. In fact, it scared me out of bed….twice! I admit, never expected that the multimedia web would bring me troubled dreams.

  • Why HSBC Sucks

    (This post includes my specific complaint about HSBC’s failure to close my account after I had paid my balance. However, over time, I have expanded this post to include helpful information for US consumers about how to fight the business practices of HSBC).

    If you are an American and have a problem with an HSBC-backed credit card, you probably only need to read my Tips for Handling a Dispute with a Credit Card Company.

    March 9, 2009 Update: I have just started the www.hsbccreditcardsucks.com website. It is now dead, but here is a summary of what is said:

    10 Reasons Why HSBC is the world’s worst credit card

    1. HSBC doesn’t respond to written correspondence sent to them by post.
    2. HSBC will not provide a copy of the credit card agreement upon request, either on the website, or via post.
    3. HSBC does not provide written information on their website about how to pay off a final balance and close the account for good.
    4. HSBC is linked to Household International, a credit card issuer well-known for its predatory lending practices (It settled a $486 million lawsuit with 46 states in 2002). HSBC integrated with Household International in 2003, and some allege that the current HSBC uses many of HI’s unsavory business practices.
    5. HSBC has a contact form which (in my experience) works rarely. Even when it does work, HSBC doesn’t allow you to have a record of emails you have sent to them (except by cutting-and-pasting onto a MS Word document).
    6. HSBC disregards legal contracts. In my individual case, HSBC agreed to a written counteroffer I made to resolve our dispute, but then promptly disobeyed the terms of it.
    7. When you dispute a charge in writing, instead of actually investigating the complaint, HSBC will send a generic reply which shows no evidence that it actually investigated the item being disputed.
    8. HSBC will not investigate your account after you have complained to a credit-reporting agency. HSBC is legally obligated to take action and contact the customer. In my specific case, HSBC sent a generic reply refusing to take any action until I provided documentation (This was long after I had sent them lots of documentation already).
    9. HSBC (like many other banks) gambled and lost billions of dollars on subprime mortgages.
    10. Recent complaints have shown that HSBC has raised interest rates and lowered credit limits to a dollar amount dangerously close to a customer’s current balance. This practice may not be illegal (and other credit cards seem to be doing the same thing), but it increases the likelihood that HSBC will award itself over-the-limit fees which result from it.

    ************************************ (my original post)

    Ok, HSBC, this means war!

    I closed this account by paying the balance in full as quoted by the customer service rep. (She quoted an amount higher than the current balance, saying that some interest changes hadn’t been factored in).

    I sent an email to them confirming my request to cancel the account. I received an email confirmation from a HSBC representative. So what happened?

    HSBC added $7 to the $0 balance, and when I protested, they added $20 late charge. I have sent these guys 3 certified mails. Here is what I have gathered:

    1. They simply do not read their mail (negligence as a matter of corporate policy).
    2. Their contact/email form has been broken (except for the first time I tried). Incompetence bordering on negligence.
    3. They made it next to impossible to obtain a copy of the original legal agreement to know exactly what the agreement is. (Deceptive trade practice).
    4. They accepted a counteroffer I made and then refused to admit that they did this. Hey, guys, I have the check as evidence! (dishonesty, deceptive trade practice).
    5. They failed to follow the terms of the counteroffer which they agreed to.. (deceptive trade practice).

    You may ask, why did I have to resort to send certified mails and counteroffers? The plain fact is that they never responded to a single correspondence of mine; I had no choice.

    Now they are ruining my credit report. Every month they award themselves the right to impose a fee of $20. Now it is $120. I know they don’t have the right to this. And if someone with half a brain were to look over the facts, they would be inclined to agree.

    I have dealt with many unscrupulous banks and credit companies. So far AT&T,  Citibank  are the worst. Chase has good customer service, but their promotions are just as tricky to figure out. But what HSBC has done in the last 6 months to me is much worse than all the banks combined.

    Here is where it gets interesting. This time, after having been burned once or twice, I know how to keep notes punctiliously. The facts are on my side, and I am determined to seek damages from HSBC, whatever the cost.

    If you have other HSBC horror stories to relate, feel free to relate them here.

    Update: February 25 2009. Wow, so much has happened over the past few months. And so little.

    First, let me offer concrete advice. when dealing with a national bank, file a complaint with the Office of the Comptroller of the Currency as soon as possible! They are located at gethelpwithmybank.gov; they are a federal institution set up precisely to handle disputes between the credit cards and consumers. They have a PDF for filling out, and the credit card is required to provide a written response to an OCC complaint within 2 weeks. You should do this first when you have a complaint. If I had known about it when I started my complaint, I would have definitely tried that avenue. Helpwithmybank also gave great information and advice about how to handle these kinds of disputes.

    Second, if you are dealing with any credit card company, you need to keep diligent records. I recommend creating a free account at Google Docs. Then note any conversations with telephone reps and include copies of any correspondence with HSBC in a single file. Google docs keeps versioned date-stamped versions of this document, so you could demonstrate when you made notations. Of course, anyone could question the legitimacy of a document, but the Google Doc datestamp is likely to be persuasive. Importantly, when you send correspondence to HSBC with confirmation of delivery, you should type the numbers of the tracking code into the Google Doc.

    Third, HSBC messed up my credit score and in fact have never sent any kind of response to my correspondence. If anything, they simply send non-specific denials and requests for information. Hello, I thought I already did that.

    I decided to file a lawsuit against HSBC, but there were several extraordinary circumstances relating to my case, so I would not recommend this strategy for everybody. Instead, for Americans, I would recommend filing a complaint with the OCC as soon as possible! Here is a FTC Summary of all the Credit Card obligations under Fair Credit billing (highly recommended). Here are  many FTC consumer guides about credit cards (in PDF form) for free download.

    A commenter made me aware of a scam reporting site with lots of complaints about HSBC specifically (including a lot of complaints from different countries).

    Here’s an article about how much money HSBC has gambled and lost on subprimes (Hint: it’s a lot).  Here’s a series of posts of people who have sued HSBC..and won! (in UK at least). Here’s the larger UK forum about HSBC. These two links don’t apply to US, but it is heartening to see the groundswell of complaints against HSBC.

    Here’s a US-based credit card forum specifically about HSBC.   Here’s a list of complaints by people in the US about HSBC-related problems.

    Here is contact information for serving legal documents (valid as of February 28, 2009)

    HSBC Bank Nevada, NA
    c/o Walter Menezes
    1441 Schilling Place
    Salinas CA 93901

    One detail: This address may be for HSBC, which has several entities.  The defendant is HSBC Bank Nevada, NA. You can call  HSBC Executive Decisions department at 800 753 6529 ext 2608 to find out whether this information is specific for your situation. The headquarters is in Illinois, so it can be very confusing.

    Finally, two interesting bits from the Office of the Comptroller of the Currency:

    I  currently have a billing dispute regarding my credit card / personal line of credit / home equity line of credit. While the dispute was under investigation, the bank reported my account negatively to the credit-reporting agencies. Can it do this?

    No. Generally, if you have filed a proper billing error dispute with a national bank, the bank shall not make an adverse report to any person about your credit standing.The bank also should not report that an amount or account is delinquent because you failed to pay the disputed amount—or related finance or other charges—while the investigation proceeds. If your bank has made a negative report despite your having filed a billing error dispute, you should file a written complaint with our office.

    I am suing the bank. Should I serve the registered agent?

    National banks do not have “registered agents.” Therefore, matters relating to registered agents should be directed to the specific bank’s president. Please contact the bank directly to obtain the name and business address of the president.

    You can file a complaint with the FTC (it’s a very nice easy-to-complete interactive form). If you file such a complaint, however, it will help the FTC but it does not resolve individual complaints.  For this reason, I still recommend filing a complaint with the OCC.

    By the way, I feel compelled to recommend a credit card I do like. Amalgamated Bank of Chicago. I’ve had this card for 15 years, and they have never given me any hassle about anything!  And their interest rates are low too. Read this Motley Fool article for what to look for in a credit card.

    February 26 Update. Wow, it turns out that HSBC missed the deadline to send a response to my petition. I am theoretically eligible for a default judgment. Wow, I didn’t expect this.

    February 28 Update.  HSBC made a reply, and the court date is early April.

    February 28 Update 2. I am keeping a log of  similar complaints I find on ripoffreport and other credit card forums.

    March 1 Update. Household HSBC Watch is a blog/news source dedicated to covering the abuses/misbehavior by HSBC Bank in USA.  This is probably the most comprehensive news source for US-related incidents. See complaints related to credit reports,  and  payment-issues.  Apparently in the 1990s HSBC bought a company known for fraud called Household International, and the blogger explicitly accuses them of continuing the same predatory practices.  From this amazing article:

    If you have a merchant credit card such as a Best Buy card, or any HSBC credit card, you may find yourself at risk. The question is ‘Who Does HSBC Hurt Financially’. Worded another way people want to know how HSBC picks their targets. Which families get lower credit scores after dealing with HSBC? Which people with HSBC credit cards head for financial ruin? The answer is that HSBC, through HSBC Finance Corporation, targets people by opportunity, not by their credit score.

    Trend analysis shows a ’slaughter window’ which is defined as anything within one week of a balance due. Just like the battlefield, HSBC Finance sends customers to the slaughter window by sending letters indicating when their interest free period is about to end. The shady part of these notifications is they DO NOT get to the customer until it is too late. In cases where the customer calls for a pay off HSBC simply lies to the customer! Lying comes in two or more formats, as shown below in a real life true example.

    You need to know that HSBC Finance was once stained, sullied, embarrassed and bottom dwelling predatory lender Household International. Answers come into focus. In the past HSBC would quote a payoff, add $15 for a phone payment, take the payoff and the following month they would bill the customer for $15 plus all the interest due – a questionable and shady tactic at best. The customer did not know to add $15 more to the quoted payoff. Welcome to HSBC’s slaughter window. Today HSBC adds the $15 as a new purchase, further clouding the problem. Like leading customers to slaughter a combination of notices that arrive late and additional charges puts one at a disadvantage. Then consider the fine print of the HSBC Finance Corporation contract and there is little one can do.

    They were accused of hounding soldiers in Iraq and of  adding late fees before the deadline occurs. Another quote from the home page:

    Many of HSBC’s problems stem from their purchase of predatory lender Household International. That is why we started watching HSBC. There were very few changes at the old Household International, now called HSBC Finance, and that is the responsibility of HSBC corporate decision makers. “They sit on checks until a late fee kicks in,” Eggert said. “Then you do what they call pyramiding: When the next payment comes in, they apply it to the late fee and say the borrower didn’t make a whole payment. And then they collect more late fees or foreclosure fees.”

    March 1 Update #2. Consumer Affairs lists these complaints from American consumers about HSBC credit cards.

    April 15, 2010. Sorry for not updating! Last year I reached a settlement with HSBC that I am happy with. I think the settlement provided redress for my complaint and compensated me for my time and inconvenience. See my Tips for Handling a Dispute with a Credit Card Company.